
x
Thinking about buying salvage cars for sale from local or online auctions, but unsure about costs, paperwork, and real-world risks? This guide helps you weigh total purchase expense, title and registration hurdles, and when a damaged vehicle is only worth keeping for parts.
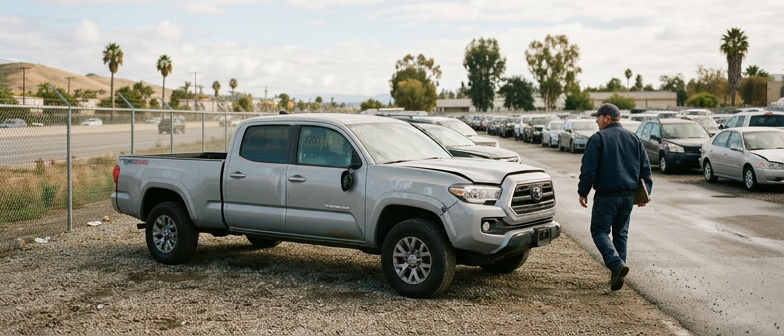
When you see salvage cars for sale, the vehicle has usually been declared a total loss by an insurer after a serious accident, fire, flood, or heavy theft damage. Instead of returning to normal retail channels, it enters the salvage system and is sold at auction to dismantlers, rebuilders, and public buyers who accept added risk. If you are in California and considering a first purchase, you need a basic grasp of what a salvage designation means for future repairs, insurance, and registration before deciding whether to bid.
Most beginners start by checking public salvage vehicle auctions near them or browsing large online salvage car auction sites that list inventory from insurance companies and towing yards. Whether you can bid on salvage cars yourself depends on each auction’s rules and state regulations: some California auctions admit public bidders, while others require a dealer or dismantler license. Before you register, review membership rules, fees, and any limits tied to salvage titles so you know who may participate, how bidding works, and what obligations you take on after winning a salvage vehicle.
When you look at salvage cars for sale, the total cost to buy a salvage car is far more than the winning bid. You must include the auction registration fee for salvage cars, buyer and gate charges, and any online bidding surcharges. Transport from the yard to your home or repair shop can be expensive, especially when the vehicle has to be towed. After the purchase, you still pay for inspection, repairs, parts, and the extra title and registration steps required for a salvage vehicle.
Many first time buyers ask whether they need a salvage car broker to manage these costs and procedures. A broker or experienced dealer can estimate realistic repair bills, assess frame or structural work, and guide you through auction rules, but their commission increases your total outlay. If you bid on your own, you avoid that fee but risk underestimating damage, missing paperwork, or misreading auction conditions. Set a firm budget that covers purchase price, all fees, transport, expected repairs, and a contingency amount so the project does not exceed the car’s likely value.
The main financial risks of buying a salvage car come from uncertainty. Hidden mechanical or safety problems can turn a cheap bid into a money pit, and some insurers may limit coverage or decline comprehensive policies on heavily damaged vehicles. Resale value is usually lower than for clean title cars, and extra inspections and compliance steps add cost before you can register the vehicle. If you misjudge the total cost or skip professional advice, any savings from the auction can disappear, leaving you with a car that is hard to insure, sell, or confidently drive.
| Approach | Upfront Costs And Fees | Process Complexity | Financial Risk Level | Best For |
|---|---|---|---|---|
| Bid directly at salvage auction | Lower fees, more variable total cost | High, self-managed steps | High, easy to misjudge repairs | Experienced DIY buyers |
| Use a salvage car broker | Higher due to commission | Lower, guided through rules | Medium, better cost estimates | Cautious first-time buyers |
| Hybrid: self-bid with limited advice | Moderate, selective broker help | Medium, some support | Medium to high, depends on discipline | Budget-focused but flexible buyers |
| Online salvage car auction only | Added online surcharges | Medium, digital paperwork | Medium, depends on research | Buyers comfortable with online tools |
Some Salvage Cars For Sale are so damaged or incomplete that repair and registration are unrealistic, and they should be treated purely as parts only cars for sale. In this case the total cost to buy a salvage car is based on the components you can actually strip, reuse, or resell, not on inspections, insurance, or road use. This parts‑focused approach avoids some common risks of buying a salvage car, such as investing in structural repairs that later fail inspection, but it creates others, including overestimating resale value, missing hidden damage in key mechanical items, or misjudging the time, tools, and storage needed to dismantle and handle the vehicle profitably.
When you look at salvage cars for sale, the key issue is how the title changes after a total loss. A salvage title is issued when repair costs exceed the vehicle’s value and it is declared uneconomical to fix. A rebuilt or revived salvage title is granted after the damaged vehicle has been repaired, inspected, and approved for road use. A car with a salvage title is usually not legal for everyday street driving until it is rebuilt, while a rebuilt title shows the vehicle passed safety and identity checks and permanently discloses its prior total loss status.
To move a vehicle into salvage or rebuilt status, you must gather the documents needed for a salvage title and any later rebuilt application. Common requirements include proof of ownership such as the previous title or insurance paperwork, government-issued ID, and total loss settlement documents from the insurer. When the vehicle is repaired, many states also require receipts for major parts, bills of sale from dismantlers, and inspection reports before issuing a revived salvage title. Complete paperwork makes it easier to register a salvage vehicle and reduces the chance that authorities question where the car or its parts came from.
A salvage car with no documents is much harder to bring back into the system and may end up limited to parts-only use. Without a valid title and proof of ownership, you might not be able to obtain a new salvage title, and in some places the vehicle can only be dismantled, not registered. Even with partial paperwork, expect extra identity checks, bonding requirements, and scrutiny over possible theft or liens. Because missing documents increase the legal and financial risks of buying a salvage car, many buyers treat these vehicles mainly as sources of components unless a clear route to proper titling and registration is confirmed in advance.
If you buy a salvage vehicle and want it back on the road in California, first understand salvage title versus rebuilt title. A salvage title means the car was a total loss; a rebuilt title applies after repairs and required inspections are completed. Before starting registration, make sure the car is structurally sound, repairs are documented, and the Vehicle Identification Number matches your purchase records, or the DMV may treat it as a salvage car with missing documents and refuse to process it.
To register a salvage vehicle, gather the documents needed for a salvage title and revived registration. You usually need proof of ownership from the auction or seller, a title application, receipts for major parts, and inspection forms from brake and lamp checks and any Highway Patrol identity inspection. The DMV calculates fees and tax and then updates the record from salvage to rebuilt title, allowing the vehicle to be legally driven.
If you are new to salvage cars for sale, decide whether to use local public salvage vehicle auctions near you or major online salvage car auction sites. For walk-in auctions, confirm in advance whether you as a private buyer can bid on salvage cars or if only licensed dealers are allowed, and bring the ID and payment type the auction requires. Online platforms usually ask you to open an account, pay an auction registration fee for salvage cars, and accept terms covering buyer premiums, storage, and payment deadlines. Before bidding, compare similar damaged vehicles, set a strict maximum bid, and include transport, repairs, inspections, and registration so the total cost to buy a salvage car stays within your budget.
Because the risks of buying a salvage car are higher, be disciplined about inspection and paperwork. Check photos and condition reports for frame damage, airbags, flood signs, and missing VIN tags, and avoid any salvage car with no documents or unclear history. Use a trusted mechanic or paid inspector when possible and do not bid on parts-only listings if you plan to put the vehicle back on the road. Confirm that local rules allow you to register a salvage vehicle, understand how a salvage title versus rebuilt title affects insurance and resale, and only consider using a salvage car broker if the auction process still feels confusing after careful research.
What does it mean when a vehicle is listed as a salvage car for sale at auction?
It means an insurer declared it a total loss after major damage, so it enters the salvage system and is sold cheaply but with higher repair, insurance, and registration risk.
Can I bid on salvage cars at public auctions near me, or do I need a broker?
Policies differ. Some public salvage vehicle auctions accept private buyers who pay a registration fee; others only allow licensed dealers or a salvage car broker to place bids.
What documents are needed to get a salvage title and later register the vehicle?
You usually need proof of ownership, total loss documents from the insurer, repair invoices, a VIN check, and any required safety or identity inspections before a rebuilt title and registration are issued.
How does a salvage title differ from a rebuilt title when buying from online auction sites?
A salvage title shows the car is a total loss and typically not legal for daily road use. A rebuilt title means it was repaired, inspected, approved for driving, but the salvage history stays on record.
What are the main cost and risk factors when buying a salvage car with no documents?
Besides your winning bid, expect auction and buyer fees, transport, repairs, inspections, and title work. Missing paperwork can cause legal problems, extra expense, and sometimes make registration impossible.