
x
If you’re trying to budget diabetes monitor costs, this guide compares the monthly price of CGMs versus blood glucose meters, explains what drives out‑of‑pocket expenses without insurance, and shows how coverage rules and HSA/FSA eligibility can lower what you pay.
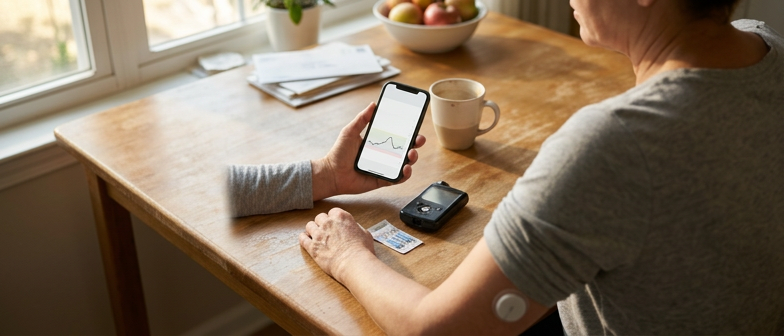
Diabetes monitor cost usually falls into two groups: traditional blood sugar meters and continuous glucose monitoring systems. A basic meter has a lower one-time price, often under fifty dollars, and is sometimes offered at low cost or through community programs. The real blood sugar monitor cost comes from test strips and lancets you buy regularly. Continuous glucose monitors have higher upfront prices for sensors and transmitters, and each sensor is worn for a limited time, so your diabetes monitor monthly cost is shaped by how often those parts need to be replaced.
Your overall monthly spending depends on how often you check glucose, which device you choose, and how much your health plan helps pay. Meter users mainly budget for strips and lancets, while people wearing a CGM focus on sensor replacement cycles and possible transmitter or reader updates. Insurance coverage, discount programs, and the ability to use HSA or FSA funds can change what you pay out of pocket. Knowing these patterns in advance helps you compare options, estimate a realistic monthly budget, and decide whether a lower upfront expense or more predictable ongoing monitoring costs fit better with your diabetes care.
For adults considering a continuous glucose monitor, the main drivers of diabetes monitor cost are the sensors, transmitters, and any receiver or phone app. Sensors are replaced every one to two weeks, creating a predictable diabetes monitor monthly cost. When you look at CGM cost without insurance, you pay full retail for each box of sensors plus any reusable transmitter, which usually makes a CGM more expensive up front than a basic blood glucose meter, even though it provides more continuous data.
Health insurance and Medicare can lower what you pay, but they often add CGM prior authorization requirements. Your prescriber may need to document your diagnosis, current treatment, and medical need before coverage is approved, especially for adults who are not on multiple daily insulin injections. Some plans limit coverage to people who meet specific clinical criteria, so the same CGM can lead to very different out‑of‑pocket costs depending on your benefits and whether authorization is granted.
When estimating ongoing diabetes monitor monthly cost, add up copays or coinsurance for sensors and transmitters and check whether your plan treats the CGM as durable medical equipment or as a pharmacy item. If you use a health savings account or flexible spending account, CGM supplies and other glucose monitoring tools are usually eligible expenses, which can soften the impact of paying full price or facing a high deductible. Reviewing your policy’s authorization rules and talking with your care team about lower‑cost options like finger‑stick meters can help you balance total cost with the level of glucose detail you want.
| Scenario | Typical Out-of-Pocket Level | Prior Authorization Impact | Monthly Cost Predictability | Use of HSA/FSA |
|---|---|---|---|---|
| CGM without insurance | High | None but full retail burden | Moderate, driven by sensor replacement | Helpful if eligible expenses confirmed |
| CGM with insurance, authorization approved | Medium | Supports access but adds paperwork | Higher, based on copays or coinsurance | Often used to smooth remaining costs |
| CGM with insurance, authorization denied | High to very high | Restricts coverage, more self-pay | Low, subject to benefit appeals | Important tool if deductible or denial present |
| CGM treated as durable medical equipment | Medium, varies by plan design | Common, linked to medical-necessity rules | Moderate, tied to equipment benefit limits | Useful when equipment costs hit budgets |
| CGM treated as pharmacy benefit | Medium | Present but often streamlined | Higher, aligned with drug tier copays | Frequently used for routine sensor purchases |
| Switching to lower-cost finger-stick meter | Low to medium | Minimal, usually no special review | Moderate, depends on strip use | Can offset reduced CGM coverage |
Continuous glucose monitors are increasingly used by adults not on insulin to track blood sugar patterns and guide lifestyle or oral medication changes. Because full coverage is often reserved for people using insulin, these adults may face higher out‑of‑pocket diabetes monitor cost, paying more for sensors and transmitters each month. Before starting, ask whether your situation meets medical‑necessity criteria, such as frequent lows or trouble controlling A1C, and how that affects CGM prior authorization requirements. Also check whether your plan treats CGM as durable medical equipment or a pharmacy benefit, since that classification can change copays, deductibles, and overall CGM cost without insurance or with limited coverage.
Traditional finger-stick blood glucose meters usually have the lowest upfront diabetes monitor cost. A basic meter is inexpensive, and pharmacies may bundle it with test strips. Most of the blood sugar monitor cost comes from ongoing supplies such as strips and lancets. Prices differ by brand and store, but many large retailers and warehouse clubs sell house-brand meters with lower-cost strips, which can reduce the monthly cost for people who test several times a day.
You can buy a blood glucose meter nearby by visiting chain pharmacies, supermarket pharmacies, or local drugstores, where meters are stocked on open shelves in the diabetes care section. They are also widely sold online with options for in-store pickup or home delivery. These nonprescription glucose monitor options are regulated but available over the counter, so you can choose based on ease of use, display readability, memory features, and strip pricing without a prescriber visit.
Because this chapter focuses on diabetes monitor cost, it helps to know that many people can use tax-advantaged accounts to manage the ongoing expense of strips and lancets. In the US, meters and their supplies are generally eligible under HSA and FSA plans when used to diagnose or manage diabetes. Reviewing your plan’s glucose monitor eligibility list, saving receipts, and buying through pharmacies that provide detailed statements can make reimbursement easier and lower the effective long-term cost of traditional monitoring.
If the monthly diabetes monitor cost feels high, using a Health Savings Account or Flexible Spending Account can make it more manageable because many glucose monitors, test strips, and continuous glucose monitoring supplies qualify as eligible medical expenses. Before you pay, confirm HSA and FSA glucose monitor eligibility with your employer benefits documents or plan administrator, and check whether you need a prescription or diagnosis code for a CGM or traditional blood sugar meter. Keep all receipts and documentation for sensors, transmitters, and related supplies, since accurate records help if your plan requests proof that the purchase was medically necessary and directly tied to diabetes monitoring.
When you look at overall diabetes monitor cost, the first big choice is a continuous glucose monitor or a traditional blood glucose meter. CGMs usually have higher upfront device costs plus ongoing sensor and transmitter expenses, while finger‑stick meters are cheaper and test strips drive most blood sugar monitor cost over time. Insurance coverage, deductibles, and whether you can pay with HSA or FSA funds can change which option is cheaper each month, so it helps to estimate how many times you check glucose daily and how often you replace sensors or strips.
Cost is only part of the trade‑off. CGMs provide ongoing trends, alerts, and fewer finger‑sticks, which can make daily life and long‑term glucose management easier for many adults. Traditional meters can still be a good fit for people who test less often, want a simple low‑cost device, or need a backup when a sensor reading seems inaccurate. Discussing your glucose targets, budget, and comfort with technology with your care team can clarify whether a CGM, a standard meter, or using both offers the best value for your health and wallet.
What mainly determines the monthly cost of a diabetes monitor?
Meters are inexpensive, but strips and lancets drive ongoing cost. CGMs have higher monthly expenses because sensors and transmitters must be replaced on a schedule.
How much can a CGM cost without insurance?
You pay full retail for each sensor box and any transmitter or receiver. Overall, CGMs usually cost far more out of pocket than a basic blood glucose meter.
Can adults not using insulin get a CGM, and what about prior authorization?
Some adults not on insulin can get CGMs, but many insurance plans require medical‑necessity documentation and prior authorization, which affects what you pay.
How should I compare CGM readings with a standard blood glucose meter?
Meters give single finger‑stick values and are very accurate when used properly. CGMs show trends but can be off during rapid changes, so confirm strange CGM results with a meter.
Can I use HSA or FSA funds for diabetes monitoring costs?
In the US, most blood sugar monitors, test strips, and CGM supplies qualify for HSA and FSA reimbursement. Check your plan’s rules and keep receipts for documentation.