
x
If you’re a small or sole trader business weighing up a merchant account, it’s hard to judge fees, contracts and payout speed. This guide helps you compare providers like Square, SumUp, Worldpay and Stripe, understand online card costs, and decide what suits in‑person or online trading.
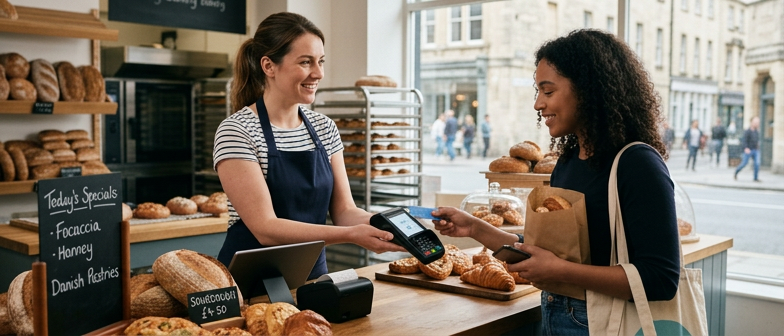
For a small firm, a merchant account is the bank facility that lets you accept card payments and digital wallets, whether a customer taps a machine on your stall or pays through your website. Instead of money going straight into your normal business bank account, it is routed into this separate account, where the payment is authorised, processing and card scheme fees are calculated, and fraud checks can be applied. This is why a dedicated merchant account for small business owners, including a merchant account for a sole trader, is treated differently from a personal account and usually comes with its own terms, pricing and support for chargebacks.
If you sell online, a merchant account for an online business performs the same role but is plugged into a payment gateway or platform that handles your checkout and security. You may see this bundled as a single service when setting up online card payments for small business use, even though funds still sit in a separate underlying account before payout. The time it takes to move money from that account into everyday business banking is called the settlement time, and merchant account settlement times can range from the same or next working day to several days, directly affecting your cash flow.
When comparing merchant account providers for a small business, look beyond headline card fees and focus on how the arrangement works day to day. A practical UK comparison should cover how long you are tied in, how quickly you receive your money, and whether the pricing fits your turnover. This matters for sole traders and very small firms trying card payments for the first time, who often need the flexibility to scale up or stop without heavy penalties.
Contract length is a major difference between providers. Traditional acquirers often use fixed terms, and it is common to see merchant account contract length in the UK of 12, 18 or even 36 months, sometimes with separate conditions for the card machine. Early exit fees, auto‑renewal and equipment return rules can all change the real cost of taking cards. By contrast, some newer services use rolling monthly terms with no long minimum period, which can suit seasonal traders or new online businesses that want to test the waters first.
Settlement speed is the other key element to weigh up. Merchant account settlement times can range from same‑day or next‑day funding through to several working days, depending on the provider and plan. Some services promote next‑day card payment settlement in the UK as standard, while others charge extra or only offer faster payouts once your trading history is established. For cash‑sensitive retailers and online sellers, this timing can directly affect stock, payroll and general cash flow, so payout terms deserve as much attention as the quoted card fee.
| Provider type | Typical contract style | Settlement speed tendency | Flexibility for small firms | Best suited trader profile |
|---|---|---|---|---|
| Traditional acquirer | Fixed multi‑year term | Slower to moderate payouts | Lower flexibility, exit penalties possible | Established retailers with stable turnover |
| App‑based pay‑as‑you‑go | Rolling monthly, minimal tie‑in | Often faster or next‑day focus | High flexibility, easy to pause or scale | Market stalls and seasonal traders |
| Online‑first gateway | Mixed terms, often usage based | Moderate, may vary by history | Flexible for growing web shops | New online businesses testing demand |
| Bank‑linked merchant account | Formal contract with reviews | Moderate, aligned to banking setup | Medium flexibility, process led | Sole traders wanting everything in one place |
With a merchant account for small business from a traditional acquirer such as Worldpay, the widely advertised 18‑month minimum contract is a fixed period during which you keep paying monthly and gateway fees even if your takings fall. In the UK, merchant account contract length usually runs from the date your facility goes live, and leaving early can trigger termination charges plus costs for card machine rental or other linked services. For a start‑up or seasonal trader this means weighing the stability and tailored pricing of a long agreement against the risk that your trading pattern or preferred provider changes before the initial 18 months end.
For a small business choosing card payments, a key decision is whether you mainly sell in person or online. Square and SumUp pair a simple card reader with pay‑as‑you‑go pricing and usually no long contract, which can suit market stalls, pop‑up shops and mobile services. Stripe and Worldpay are better seen as merchant account providers for online business, with tools for taking payments through websites, apps or invoice links, and more options for custom integration if you have technical help.
In a UK comparison of merchant account providers, it helps to look past the headline percentage rate. Square and SumUp tend to keep fees straightforward for small in‑person traders, which can make budgeting easier when you are just starting to accept online card payments for a small business as an add‑on to a physical trade. Stripe focuses on internet and app‑based payments, supports many currencies and payment methods, and is widely used by smaller e‑commerce brands. Worldpay is more traditional, may involve a dedicated merchant account and tailored package, but this can come with setup checks and in some cases separate gateway and processing charges.
Flexibility and contract length matter as your business changes. Square and SumUp typically avoid long minimum terms, so you can scale with seasonal trade and test card payments with limited commitment. Stripe is usually flexible as well, which is why many merchants weigh up Worldpay or Stripe for small business use, especially for online‑only ventures. Worldpay has often used fixed‑length contracts, which might suit you if you want a negotiated rate and are confident about turnover, but is less appealing if you prefer to keep your merchant account easy to switch and manage day to day.
When a small firm opens a merchant account for online business, the main cost is usually a percentage fee on each card payment, sometimes with a fixed pence amount added. Online card payment fees in the UK are often higher than in person rates because of fraud and chargeback risk, and you may also pay extra for authorisation, refunds, chargebacks or payment gateway access, so the real cost is the total of all these items.
For online card payments for small business, the choice is usually between simple bundled pricing and lower effective rates at higher turnover. Flat fee platforms include the gateway, fraud tools and settlement in one price, which is easy to budget but can become expensive as volumes grow. Traditional merchant account pricing can be cheaper per transaction at steady volumes, but monthly minimums and fixed fees can penalise very low usage.
For a small market trader taking cards face to face, the key choice is how the card machine links back to a merchant account for small business use. App‑based terminals running over 4G or Wi‑Fi suit markets and pop‑ups and usually charge a flat percentage per transaction, which keeps pricing simple but can be costly if your average sale is high. A traditional merchant account with a countertop or portable terminal may offer lower card machine fees for a regular trader, but often adds monthly rental, minimum charges and longer commitments, so the total cost must be judged against how often you trade.
Settlement speed is just as important as the price per transaction. With a dedicated merchant account, settlement times can range from same‑day to several working days, and some providers now offer next‑day card payment settlement in the UK, sometimes with higher fees, reserve balances or strict cut‑off times. App‑based aggregators usually bundle the merchant account and processing in one deal but may hold funds for an extra day or two, which can strain cash flow if you depend on market income for stock and travel. When comparing options, weigh per‑transaction costs against settlement speed and any funding delays that could limit your ability to reinvest takings.
What does a merchant account mean for a small or sole trader business?
It is a dedicated facility that receives card and wallet payments, runs security and fee checks, and then passes cleared funds on to your business bank account, keeping business and personal money separate.
How should I compare UK merchant account providers and contract length?
Check total costs, minimum monthly charges, any 12–18 month tie‑ins, notice periods, and whether settlement times and support suit your turnover and risk tolerance.
Is Square or SumUp better than a traditional merchant account for a small market trader?
App‑based readers with simple percentage fees and no long contract can suit occasional or seasonal trading, while conventional terminals may be cheaper per transaction but add rental and minimum charges.
What should I know about Worldpay’s 18‑month minimum contract and settlement times?
You usually pay fees for the whole term even if takings drop, and early exit can trigger penalties, so weigh that against next‑day or two‑day settlement and any tailored pricing you’re offered.
How do online card payment fees in the UK differ from in‑person payments?
Online processing via Stripe, Worldpay or similar typically attracts higher percentage fees, plus possible gateway, refund and chargeback charges, reflecting greater fraud risk and integration costs.